When and How to Report a Car Accident in Florida: Police Reports, Insurance & Deadlines
A missing police report is exactly what insurance adjusters use to shrink your payout. Here's when to report and how to protect yourself.
Written and reviewed by Jedediah “Jed” A. Main
Board Certified Civil Trial Lawyer
Published:
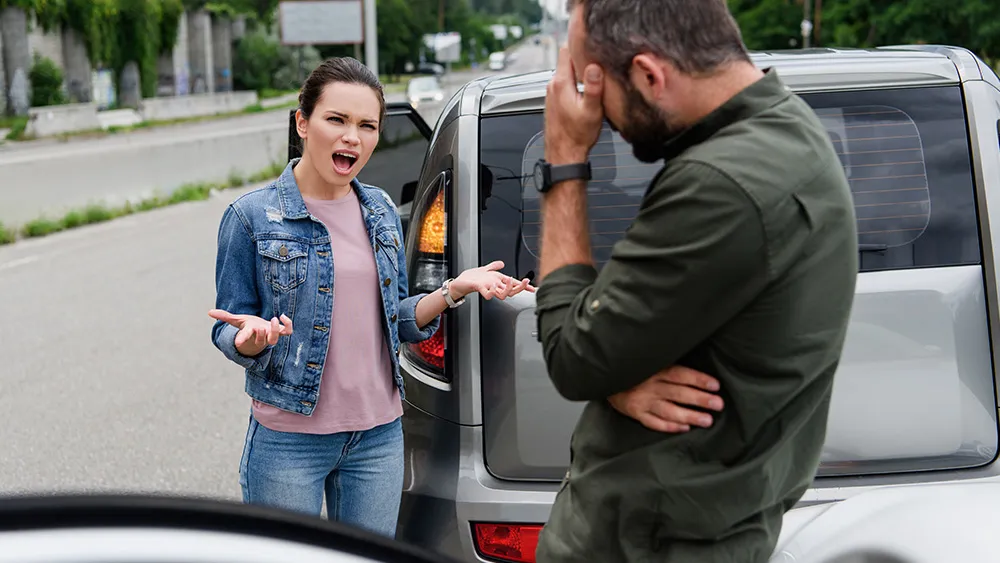
When you’re sitting on the side of a busy Orlando road or the traffic-heavy lanes of I-4 with a smashed bumper and a racing pulse, your first instinct is to get home safe. At that moment, it’s tempting just to exchange phone numbers with the other driver and walk away, but trust me, leaving without an official car accident police report is a dangerous trap. In my years fighting for injured Central Florida drivers, I’ve seen insurance adjusters use this lack of documentation to delay, reduce, or flat-out deny car accident insurance claims. This guide outlines when Florida law requires a police call, how to self-report minor crashes, how to obtain a police report, how to notify your insurance provider, and the strict legal deadlines you need to protect your claim.
When Are You Legally Required to Call the Police After a Florida Car Accident?
Here’s something I see play out: drivers assume calling the police is optional for a minor fender bender and end up walking away without an official car accident police report. This leaves you unprotected and vulnerable to lowball settlement offers and claim denials based on “missing documentation” from insurance adjusters, while the other driver could just change their story with nothing to contradict them. Under FL Statute §316.065, you must notify the police for any crash involving injury, death, or apparent property damage of at least $500. Here’s what that means at the scene:
- Injuries, even minor ones. A stiff neck, dull headache, or bruising all count. If anyone feels pain, EMS needs to check them out, and police need to document it. I tell every client to accept the on-scene evaluation. Trust me, adrenaline hides injuries that don’t flare up until days later, and that immediate medical paper trail stops an adjuster from claiming your injury didn’t come from the crash.
- Property damage of $500+. No exact estimate needed at the scene — if the damage looks in that range, the call is mandatory.
Even when the law doesn’t strictly require it, I tell every client to call the police in three situations:
- A Hit-and-Run Driver: If the other motorist flees without exchanging information, it’s a criminal offense under Florida Statute §316.027 (for injuries) or §316.061 (for property damage). An accident report is critical for tracking them down and triggering your uninsured motorist coverage.
- Suspected DUI or Impairment: If you think the other driver is under the influence of alcohol, prescription pills, or recreational drugs, call law enforcement to document the impairment and run sobriety tests.
- A Vehicle That Must Be Towed: If a car is too damaged to drive off safely, get police to manage scene safety and document why it couldn’t be moved.
The Two-Way Street Rule: Regardless of police involvement, Florida Statute §316.062 makes exchanging information a strict legal duty that goes both ways. Don’t just grab the other driver’s info, hand yours over too. Snap phone photos of their license, registration, insurance card, both plates, any vehicle damage, and get witness numbers before they leave the scene.
The October 2026 Property Damage Reporting Threshold
Starting October 1, 2026, Florida raises the mandatory crash reporting threshold for property damage from $500 to $2,000 under Senate Bill 488 (Chapter 2026-39). The legislature bumped it up to reflect modern repair costs. But honestly? You can’t always eyeball $2,000 in damage at the scene, and it’s easy to blow past this number once a shop inspects it. Make the mistake of guessing low and skipping the report, and you’ve got two problems — a possible fine and points on your record, and no official documentation when the insurance company questions your car accident insurance claim. My rule of thumb: if you see a dent, a cracked windshield, or a deployed airbag, treat it as reportable and call.
What If Your Crash Doesn’t Meet That Threshold? Self-Reporting in Florida
If no one’s hurt and the damage looks minor, an officer might tell you to clear the roadway and handle the details yourself. This doesn’t mean you’re off the hook for submitting paperwork, though, as Florida law requires you to self-report within 10 days when there’s property damage but no investigating officer. Skip it, and you’ve handed the insurance company a reason to delay or deny your car accident insurance claim. Here’s how to do it right:
- Download the Official FLHSMV Form.
Visit the Florida Department of Highway Safety and Motor Vehicles portal and grab the Driver Report of Traffic Crash (Self Report) form.
- Fill in the Crash Details.
Complete every applicable block on the front of the sheet. You’ll need the exact time, date, and location of the crash, plus driver’s license numbers, vehicle details, and insurance information for everyone involved.
- Sign and Submit.
Sign and date the bottom of the front page, then email it to SelfReportCrashes@flhsmv.gov or mail a hard copy to the FLHSMV Crash Records Bureau in Tallahassee. There’s no fee to file. Save a copy of the form and your submission confirmation for your records.
Accident Scene Tip: I tell my clients to never leave the scene empty-handed, as the self-report form asks for specifics. Snap photos of the other driver’s license, registration, and insurance card before anyone drives off. One exception to self-reporting: a crash involving a commercial motor vehicle can’t be self-reported. Florida requires a law enforcement officer to complete a long-form report, so make sure police are called to the scene. For any other minor crash where an officer shows up but still sends you off to self-report, grab their name and badge number, and ask for a Driver Exchange of Information form to create an accurate, officer-provided paper trail for your insurance company.
How Do I Get a Copy of My Florida Car Accident Police Report?
If a police officer responded to your crash, your report gets filed with the FLHSMV and is available for purchase:
- Online via the Florida Crash Portal: It takes about 10 days to post, but I tell clients to check around day 7. You’ll pay a $10 state fee + a $2 convenience fee, and can download it right away. Note: the link expires 48 hours after purchase.
- By Mail: Mail a written request with a $10 check or money order to the FLHSMV Crash Records Bureau in Tallahassee. This skips the $2 fee but takes roughly 4 to 6 weeks to land in your mailbox.
The 60-Day Privacy Rule: Car accident police reports are confidential for 60 days, accessible only to those involved, their attorneys, and insurers. When buying online, you’ll have to select your exemption and complete an attestation to confirm you’re entitled to it. By mail, include a notarized Sworn Statement for Crash Report (Form 94010) and a copy of your ID. After 60 days, the report becomes public record.
What Insurance Notice Rules and Filing Deadlines Apply After a Florida Crash?
Many people don’t realize your insurance company isn’t automatically in your corner. Your policy has a “prompt notice” clause, and waiting too long to report gives the carrier a clean excuse to fight your coverage. Notify your insurer as soon as possible, ideally within a day or two, but only give bare facts— a crash happened, the date, time, location, and that you’re seeking medical treatment — and never give a recorded statement. That last one’s a trap, designed to lock you into an early account before you know how hurt you are. After that call, two hard deadlines decide whether you can recover compensation:
- You Have 14 Days to See a Doctor. Under Florida Statute §627.736, you must seek initial medical treatment within 14 days of the crash, or you lose your PIP benefits. I’ve seen good people lose coverage because they felt fine and waited. Don’t.
- 2 Years to File a Lawsuit. Under§95.11(5)(a), you have 2 years from your crash date to file a personal injury lawsuit. Miss it by a day and the court throws your case out — no matter how obvious the other driver’s fault was. Trust me, insurers know that the clock is ticking, and “running it down” is a tactic I’ve seen more than once.
“The deadlines are the one thing I can’t fix after the fact. Call before time runs out — the first conversation is free.” — Jed Main, Main Law Firm.
Have Questions About Reporting a Car Accident in FL? I get these same questions from clients constantly, and my answer’s always the same: protect yourself first, because the insurance company won’t.
- What If The Other Driver Pleads No Police?
In my experience, the drivers who resist calling police are usually uninsured, driving on a suspended license, or impaired. That official report is your only shield when their story changes the next morning. Call anyway.
- Will a Police Report Raise My Insurance Rates?
No — the report doesn’t set your premiums. Fault does. An official report often proves the other driver caused the crash, not you.
- What If I Don’t Have the Other Driver’s Insurance Information?
It happens more often than you’d think — things move fast, and sometimes people just drive off. Here’s what most folks don’t know: once you have your crash report, you can file an Insurance Request Form (HSMV 83392) to pull the at-fault driver’s policy number. It’s a quiet tool the insurance companies would rather you not find out about.
Been in a Florida Car Accident? Call The Main Law Firm Before a Deadline Passes
The insurance adjuster on your case has started building their file, betting you don’t know the reporting rules, deadlines, or how to get your car accident police report before it works against you. I’ve gone toe-to-toe with these insurance companies for Central Florida drivers and fought hard to get injured people the full compensation they deserve. Call me at 407-278-7423, reach out through our free consultation page, or visit our 4 Central Florida locations in Winter Park, Mount Dora, Lake Mary, and Clermont.
Legal Disclaimer: The information in this article is general and not legal advice. Past results do not guarantee a similar outcome; every case depends on its own facts and circumstances.
Share This Article
Written and reviewed by Jedediah “Jed” A. Main
Board Certified Civil Trial Lawyer
Jedediah “Jed” Main is a Florida Bar Board Certified Civil Trial Lawyer and founder of The Main Law Firm, P.L. A former prosecutor and insurance-defense attorney, Jed has represented injured clients throughout Orlando and Central Florida since founding the firm in 2010.
